


Cross-border payments move value between countries to settle trade, transfer personal funds, and support investment flows. They are the mechanism behind almost every international transaction a UK business or individual makes.
Three primary reasons they exist:
- Trade settlement — paying overseas suppliers, receiving export revenues, and settling corporate invoices across currencies
- Remittances and personal transfers — individuals sending money home or receiving funds from abroad
- Cross-border investment and financial services — buying foreign assets, funding overseas subsidiaries, and accessing international capital markets
The scale is striking. The Bank of England estimates that global cross-border payment flows will rise significantly from 2017 to 2027, reflecting ongoing growth in cross-border activity. For UK firms trading internationally, that growth is not a background statistic. It is the competitive environment they operate in every day.
What counts as a cross-border payment?
A cross-border payment is any transfer of funds where the payer and the payee hold accounts in different countries, typically involving at least one currency conversion or a cross-jurisdiction settlement step.
The category splits into two broad tiers. Retail payments cover remittances sent by individuals, consumer purchases from overseas merchants, and payroll for employees based abroad. A UK household sending money to family in Nigeria, or a freelancer in Manchester receiving a fee from a US client, both fall here. Wholesale payments are higher-value flows between banks, corporates, and financial institutions: a UK manufacturer settling a £2 million invoice with a German parts supplier, or a fund manager repatriating dividends from an Asian equity position.
Both tiers share the same underlying infrastructure challenges, but the costs and timelines hit retail users proportionally harder.
What methods move money across borders?
Several distinct rails carry international payments, each with its own speed, cost, and regulatory profile.
- Correspondent banking via SWIFT — the dominant wholesale channel. Banks exchange standardised messages through the SWIFT network, routing funds through one or more intermediary (correspondent) banks. Pros: global reach, regulatory maturity. Cons: multi-day settlement, layered fees, opacity on arrival time.
- Card rails (Visa, Mastercard) — widely used for consumer and SME purchases. Pros: instant authorisation, broad merchant acceptance. Cons: FX margins can be significant; chargebacks add complexity for merchants.
- Specialised payment providers — fintechs that pre-fund local accounts in destination countries to simulate near-instant settlement. Pros: faster, often cheaper for popular corridors. Cons: coverage thinner outside major routes.
- Real-time rail interlinking — connecting domestic fast payment systems across borders. The UK’s Faster Payments scheme and the eurozone’s TARGET Instant Payment Settlement (TIPS) are the two most relevant examples for UK businesses. Pros: near-instant, low cost. Cons: still limited to specific bilateral or multilateral corridors.
- Remittance networks — specialist services for retail person-to-person flows, often with cash-out options in destination countries. Pros: wide reach into underserved corridors. Cons: fees vary widely.
- Stablecoins and crypto rails — an emerging channel using blockchain settlement to bypass correspondent chains. Pros: 24/7 availability, programmable. Cons: regulatory frameworks are still maturing; volatility risk on non-stablecoin assets.
Who actually uses cross-border payments, and how?
The UK household sending a remittance. A family in Birmingham transfers £200 to relatives in Pakistan. Using a specialist remittance provider rather than a high-street bank typically saves on fees, though World Bank data shows the global average cost to send a typical remittance amount remains substantial in 2024. Timing: one to three business days for bank-to-bank; same-day for cash-out networks. Tip: compare FX rates, not just the headline transfer fee.
The UK SME paying an Asian supplier. A London-based e-commerce brand pays a manufacturer in Vietnam. The invoice is in US dollars. The SME needs to convert sterling, instruct its bank or a payment provider, and ensure the beneficiary details match exactly. Budget two to five business days via correspondent banking; potentially same-day via a fintech with pre-funded USD accounts in Vietnam.
The marketplace paying overseas sellers. A UK platform with sellers in 30 countries needs to batch-pay weekly. Multi-currency accounts and mass-payout APIs from specialist providers reduce manual overhead significantly.
Cross-border payroll. A UK tech firm employing remote contractors in Eastern Europe needs to pay in local currencies on a fixed date. Payroll-specific providers handle FX and local compliance, reducing the risk of late payments that breach contractor agreements.
The UK investor buying foreign assets. Purchasing shares on a US exchange or a property in Spain involves FX conversion and settlement through custodian banks. FX timing matters: a rate locked at instruction can differ materially from the rate at settlement.
Pro Tip: For high-value or time-sensitive transfers, ask your provider whether they offer a forward contract to lock in today’s exchange rate for a future settlement date. It removes FX uncertainty from your cost planning.
How does a cross-border payment actually flow?
The end-to-end journey is longer than most senders realise. Here is the typical sequence for a SWIFT-routed wholesale payment.
- Instruction — the payer submits payment details (beneficiary name, IBAN or account number, SWIFT/BIC code, amount, currency) to their sending bank or payment provider.
- Compliance screening — the sending institution runs AML and sanctions checks against the payer, beneficiary, and destination country. Incomplete or mismatched data triggers a manual review and delays the payment.
- SWIFT messaging — the sending bank transmits a standardised message (typically MT103 or the newer ISO 20022 format) to a correspondent bank in the destination currency’s home market.
- Correspondent chain — if no direct relationship exists, the message passes through one or more intermediary correspondent banks, each deducting a fee and performing its own compliance check.
- FX conversion — currency exchange occurs either at the sending bank, at an intermediary, or at the receiving bank, depending on the arrangement. Each conversion point applies a margin above the mid-market rate.
- Beneficiary-leg settlement — the receiving bank credits the beneficiary’s account. SWIFT data shows that incomplete beneficiary data is one of the main reasons end-to-end speed lags, with many messages still lacking the detail needed for straight-through processing.
- Confirmation — the payer receives a credit confirmation, though timing varies by corridor.
Common fee types to watch:
- Transfer fee (charged by the sending institution)
- Correspondent/intermediary bank fees (deducted mid-chain, often opaque)
- FX margin (the spread above mid-market rate)
- Receiving-bank fee (charged by the beneficiary’s bank)
Typical settlement times range from same-day (interlinked fast rails, some fintech corridors) to five business days (complex correspondent chains into less-served markets).
Why cross-border payments matter for the economy
Efficient international payments are not a convenience. They are infrastructure. As BIS research makes clear, payment systems are the economic plumbing, and friction in that plumbing can shave measurable percentage points off GDP.
The numbers bear this out. IMF working paper WP/25/120 estimates the combined traditional and crypto cross-border payments market approached roughly one quadrillion dollars in 2024, concentrated in advanced economies but with heterogeneous flows by currency and transaction size. For the UK, a major global financial centre, the health of these flows directly affects trade competitiveness, diaspora welfare, and capital market access.
The ECB’s analysis is particularly striking for policymakers and businesses alike. Interlinking fast payment systems raises trade by about 4% on average, with the gains concentrated in corridors where costs were previously highest. For a UK SME exporting to markets with newly interlinked rails, that is a real competitive shift, not a marginal improvement.
Remittances carry their own economic weight. For many recipient households in lower-income countries, inbound transfers represent a significant share of household income. Reducing the cost of sending £200 from the UK by even two percentage points frees up meaningful spending power.
Why are cross-border payments still slow and expensive?
The short answer: fragmented infrastructure, long correspondent chains, and compliance overhead that no single institution can fix alone.
BIS Papers No 167 identifies the structural causes clearly: institutional fragmentation, divergent messaging standards, and limited competition in correspondent banking corridors. These are not problems a single fintech can solve by building a better app.
The specific barriers:
- Correspondent chain length — each additional intermediary bank adds a fee, a compliance check, and a potential delay.
- AML/KYC overhead — each institution in the chain screens independently, with no shared data, so the same transaction is checked multiple times.
- Trapped liquidity — banks must pre-fund nostro accounts in foreign currencies across time zones, tying up capital and raising funding costs. The Bank of England notes this as a significant cost driver.
- Data fragmentation — inconsistent beneficiary naming conventions and incomplete remittance information cause exceptions that require manual intervention. SWIFT’s own data highlights the beneficiary leg as the weakest link.
- Standards divergence — legacy MT message formats carry less structured data than ISO 20022, making automated processing harder.
- Limited competition — in many corridors, only one or two correspondent banks operate, giving them pricing power.
For UK firms, the practical consequence is that payments to less-served markets (parts of Africa, South Asia, Central America) are disproportionately slow and costly. Declining correspondent banking relationships have hit smaller corridors hardest, as ECB working paper research confirms: the corridors with the highest pre-existing costs gain the most from interlinking, but they are also the ones least likely to have interlinked rails yet.
How are things improving?
Progress is real, but it requires coordination across institutions, regulators, and governments. No single actor controls the full chain.
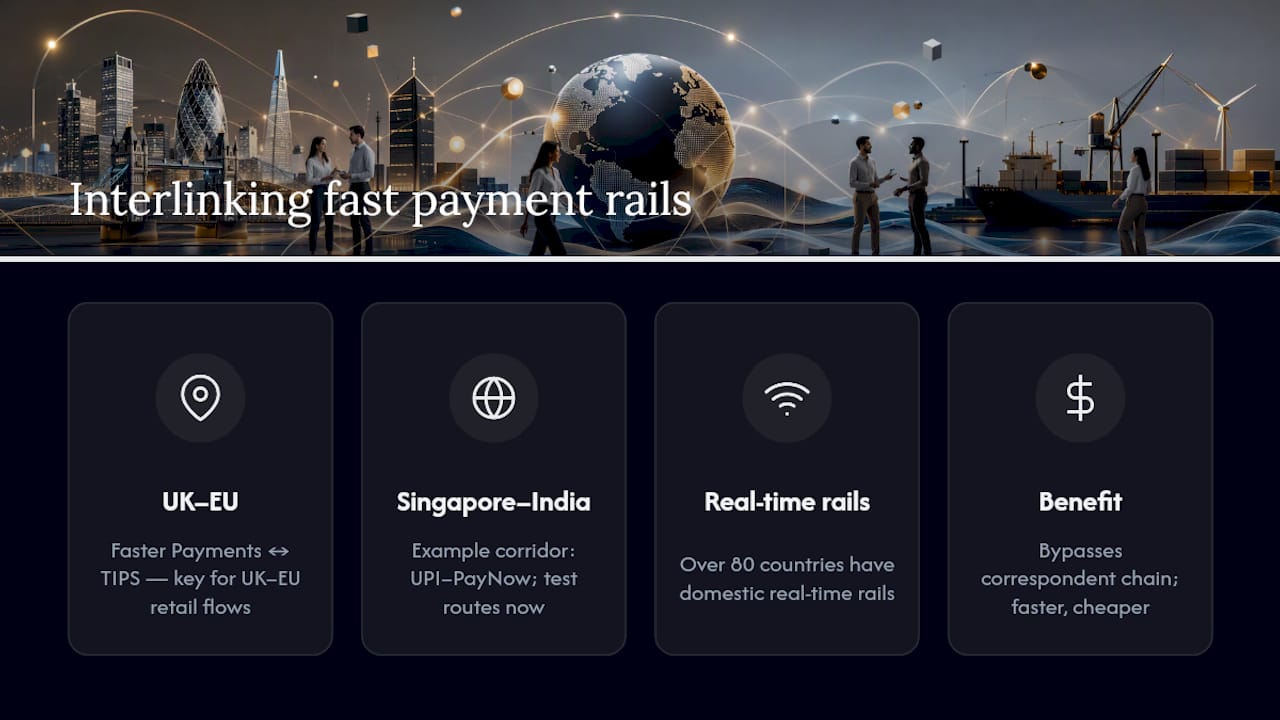
The most concrete near-term lever is interlinking domestic fast payment systems. Over 80 countries now have domestic real-time rails. Connecting them bilaterally or multilaterally bypasses the correspondent chain for retail flows. The UK’s Faster Payments and the eurozone’s TIPS are the most relevant examples for UK businesses trading with Europe. The Financial Stability Board’s G20 Roadmap sets targets for speed, cost, access, and transparency, with interlinking as a central pillar.
ISO 20022 migration is another structural fix. Richer, structured message formats reduce the data gaps that cause manual exceptions, enabling more straight-through processing across the chain.
Central bank digital currencies (CBDCs) are being explored by multiple central banks as a way to enable direct settlement without correspondent intermediaries. These remain experimental for cross-border use, but the Bank of England and others are actively researching the architecture.
On the private side, intelligent routing engines select the fastest or cheapest path for each payment in real time, and FX optimisation tools give businesses better visibility and control over conversion costs.
Pro Tip: If your business pays into corridors with newly interlinked fast rails (for example, Singapore-India via UPI-PayNow, or EU corridors via TIPS), test those routes now. The cost and speed difference versus correspondent banking can be substantial, and early adopters gain a pricing advantage.
Why language and localisation reduce payment friction
Accurate localisation and translation cut delays caused by incorrect beneficiary details, misinterpreted payment instructions, and mismatched documents. This is not a soft benefit. It is an operational one.
SWIFT data confirms that incomplete or inconsistent beneficiary information is a primary cause of exceptions on the beneficiary leg. Many of those exceptions trace back to name transliteration errors, address format mismatches, or instructions that were not adapted for the destination country’s banking conventions.
Documents and processes that benefit from professional localisation:
- Payment instructions — amounts, account details, and reference fields adapted to destination-country formats and scripts
- Beneficiary names — accurate transliteration from Arabic, Chinese, Cyrillic, or other scripts into Latin characters (and vice versa), following the conventions the receiving bank expects
- Commercial invoices — currency, tax identification, and line-item descriptions that match local regulatory requirements
- AML/KYC documentation — identity documents, proof-of-address, and source-of-funds declarations translated accurately for compliance review
- Contract terms and payment schedules — localised so counterparties understand obligations without ambiguity
- Compliance disclosures — sanctions declarations and regulatory notices adapted for the destination jurisdiction
glocco® works across fintech, legal, and e-commerce sectors, providing language services that support banking compliance and reduce the exception-handling overhead that slows international payments. Accurate translation of compliance documents, for instance, has been shown to reduce errors in EU regulatory workflows by measurable margins. For teams managing cross-border contracts and payment terms, multilingual legal communication guidance is a practical starting point.
Localisation is not a finishing touch on a cross-border payment workflow. It is a compliance and operational input. A beneficiary name that does not match the receiving bank’s records stops a payment just as effectively as an incorrect IBAN. Getting the language right, in the right format, for the right jurisdiction, is how you keep the payment moving.
glocco®’s take: one practical next step for UK readers
Cross-border payments exist because global trade, personal connections, and capital flows do not stop at borders. The infrastructure that supports them is improving, but unevenly. The gains are real where rails are interlinked and data quality is high. The friction persists where correspondent chains are long and documentation is inconsistent.
If you are a UK business making regular international payments, the single most useful thing you can do today is audit your highest-volume corridors. Check whether interlinked fast rails exist for those routes, and review your payment documentation for localisation gaps. Those two steps address the two most controllable sources of delay and cost.
Sources
- Cross-border payments | Bank of England
- Speech by Frank Smets — BIS
- Global cross-border payments: A $1 quadrillion evolving market? (IMF WP/25/120)
- Unlocking trade potential: the benefits of improving cross-border payments | ECB
- Remittance Prices Worldwide (World Bank)
- SWIFT — Data shows focus needed on beneficiary leg
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.


